- Savings
 SavingsSave regularly, from as little as £5 per month.
- Loans
 LoansHelping you by offering a range of loans for a variety of purposes, direct from your payroll.
- Mortgages
 MortgagesHelping the police family to get on and remain on the property ladder.
- Financial Wellbeing
 Financial WellbeingSome of our top tips to help you manage your money even better.
- Services and Support
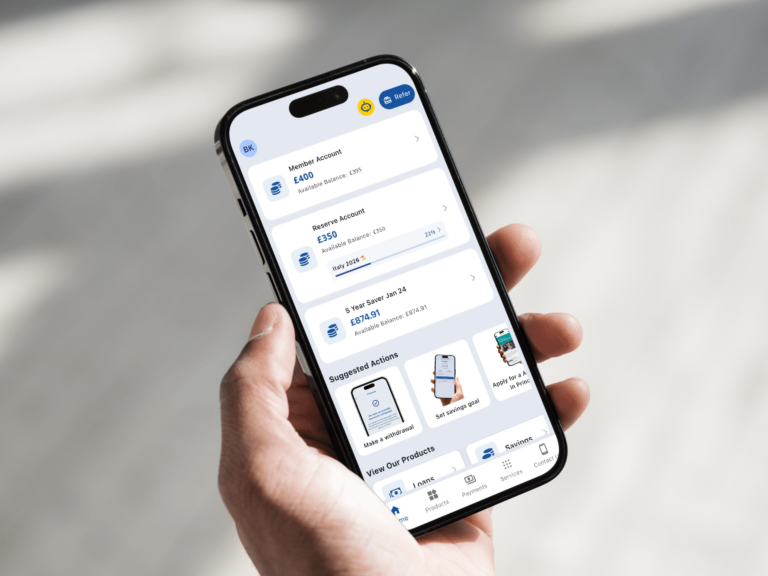 Services and SupportFind more information on the additional services or support we offer.
- About Us
 About UsFind out more about the biggest police credit union in the UK.
- Savings
- SavingsSave regularly, from as little as £5 per month.
- Loans
- LoansHelping you by offering a range of loans for a variety of purposes, direct from your payroll.
- Mortgages
- MortgagesHelping the police family to get on and remain on the property ladder.
- Financial Wellbeing
- Financial WellbeingSome of our top tips to help you manage your money even better.
- Services and Support
- Services and SupportFind more information on the additional services or support we offer.
- About Us
- About UsFind out more about the biggest police credit union in the UK.
Written by: Ben Kirkman
Category: Let's talk about money
Read Time: 4 minutes
From household bills to savings and retirement income, changes in the wider economy can affect our finances in different ways.
There have been several financial updates recently, including changes to inflation, interest rates, energy costs, earnings and the State Pension. While you may have seen these headlines in the news, it is not always clear what they mean in practice.
We’ve brought together some of the latest developments and explained them in straightforward terms, helping you understand what has changed and why it may matter to you.
Inflation remains above the Bank of England’s target
The latest figures from the Office for National Statistics show that UK inflation rose to 3.1% in August, up from 2.9% in July.
Inflation measures how the prices of goods and services change over time. A rate of 3.1% means that, on average, prices were 3.1% higher in August 2026 than they were a year earlier. However, price changes are rarely the same across every area of spending.
Some costs may increase significantly, while others may rise more slowly or even fall.
The impact of inflation can vary depending on your circumstances and spending habits.
For example, if you rely heavily on your car, changes in fuel prices may affect your budget more than someone who uses public transport regularly.
Recent figures show that transport costs, particularly motor fuel, were among the biggest contributors to the increase in inflation. As a result, some households may notice higher costs in day-to-day spending.
The Bank of England aims to keep inflation at 2% over the medium term, so inflation remains above its target level.
What could this mean for your money?
The Bank of England has kept the UK base rate at 3.75%, meaning there has been no change following its latest meeting.
The base rate can influence the interest charged on borrowing, such as loans and mortgages, as well as the interest paid on savings accounts. The impact will depend on the financial products you have and the terms that apply to them.
If you have borrowing, changes in interest rates can affect monthly repayments and the overall cost of borrowing. If you have savings, the rate offered on your account can influence how much interest you earn over time.
Different providers and accounts offer different rates, so it can be worthwhile reviewing your arrangements from time to time to ensure they continue to meet your needs.
The Bank of England has indicated that energy prices could continue to influence inflation in the months ahead. While no one can predict future changes with certainty, it is a reminder that wider economic developments can have an impact on household finances.
In simple terms, interest rates can affect two key areas of your finances:
- How much it costs to borrow
- How much interest you may earn on savings
The effect will vary from person to person depending on their circumstances.
Energy bills are changing from October
Energy continues to be one of the most significant household expenses for many families.
From 1st October, Ofgem’s energy price cap will increase by 4%.
For a typical household using gas and electricity and paying by Direct Debit, the annual cost covered by the cap will rise from £1,663 to £1,723.
It is important to remember that the price cap is not a limit on your total bill. Instead, it sets the maximum rates suppliers can charge for units of energy and standing charges on default tariffs. The amount you pay will depend on how much energy you use.
There is also a change to VAT on electricity. From 1 October 2026 until 31 March 2027, VAT will be removed from electricity bills, while gas will continue to have VAT charged at 5%.
The current price cap figures already take this VAT change into account.
What you pay will ultimately depend on factors such as your household energy usage, where you live and the tariff you are on.
The State Pension is now £241.30 a week
The full rate of the new State Pension is now £241.30 per week for the 2026/27 tax year, up from £230.25 per week in 2025/26.
The amount you receive may be different from the full rate. It depends on your National Insurance record and individual circumstances.
If you’re approaching retirement, checking your State Pension forecast can help you understand how much you could receive based on your current National Insurance record. It can also help you see how the State Pension may fit alongside any workplace pensions, personal pensions and other savings you may have.
Understanding your expected retirement income can help you make informed decisions and plan ahead with greater confidence.
Thinking about retirement?
Our Preparing for Retirement guide explains key considerations and where to find further information.
Focusing on what matters to you
You do not need to follow every financial headline to stay on top of your money.
What matters most is understanding the changes that could affect your own circumstances. For some people, that may mean keeping an eye on household bills. For others, it could involve reviewing savings, understanding borrowing costs or planning for retirement.
Everyone’s situation is different, and there is no single approach that works for everyone. Taking time to understand your finances and review them regularly can help you feel more confident about managing your money, whatever changes may be happening in the wider economy.
If you would like extra support with your finances, free and independent guidance is available from organisations such as MoneyHelper and StepChange.
This article is provided for general information only and does not constitute financial advice. Individual circumstances will vary, and you should consider your own situation before making financial decisions.
Slater House, Oakfield Road,
Cheadle Royal Business Park,
Cheshire, SK8 3GX
Cheadle Royal Business Park,
Cheshire, SK8 3GX

Stay in touch
Copyright © 2026 No1 CopperPot Credit Union
Number One Police Credit Union Limited trading as No1 CopperPot Credit Union is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority. Firm Reference Number (FRN) 213301. For details visit http://www.fca.org.uk