- Savings
 SavingsSave regularly, from as little as £5 per month.
- Loans
 LoansHelping you by offering a range of loans for a variety of purposes, direct from your payroll.
- Mortgages
 MortgagesHelping the police family to get on and remain on the property ladder.
- Financial Wellbeing
 Financial WellbeingSome of our top tips to help you manage your money even better.
- Services and Support
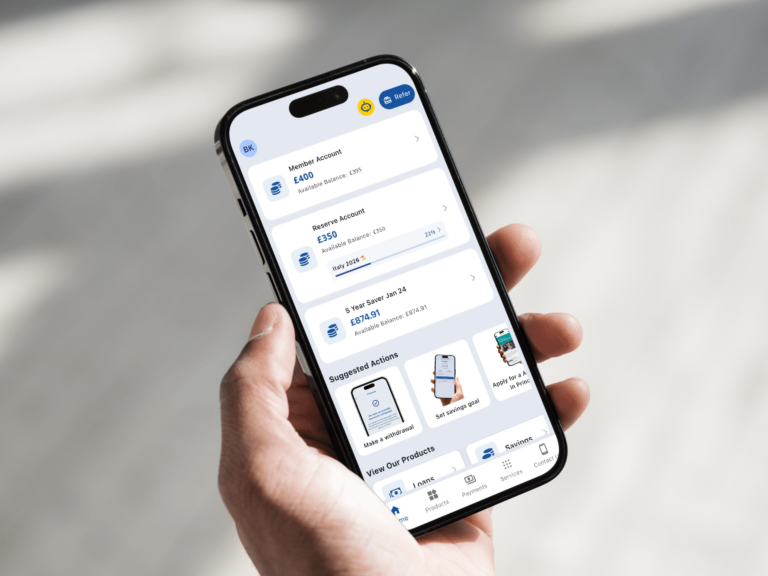 Services and SupportFind more information on the additional services or support we offer.
- About Us
 About UsFind out more about the biggest police credit union in the UK.
- Savings
- SavingsSave regularly, from as little as £5 per month.
- Loans
- LoansHelping you by offering a range of loans for a variety of purposes, direct from your payroll.
- Mortgages
- MortgagesHelping the police family to get on and remain on the property ladder.
- Financial Wellbeing
- Financial WellbeingSome of our top tips to help you manage your money even better.
- Services and Support
- Services and SupportFind more information on the additional services or support we offer.
- About Us
- About UsFind out more about the biggest police credit union in the UK.
Written by: Ben Kirkman
Category: Let's talk about money
Read Time: 5 minutes
Taking some time to check in on your finances can help you feel more prepared for what’s ahead, whether you’re saving towards something important or building a little extra breathing room for the unexpected.
We know life in the Police Family doesn’t always follow a predictable pattern. Changing shifts, overtime, family commitments and planning for retirement can all affect your finances.
Whether you’re serving, retired or part of the wider Police Family, here are nine simple steps to help you take stock and think about what comes next.
1. Start by understanding your finances
Before thinking about how much you could save, it helps to know what’s coming in and where your money is going.
Looking back over your bank statements for the last few months can be a good place to start. Make a note of your regular bills and everyday spending, as well as costs that only come up occasionally.
If your income changes from month to month, perhaps because of overtime or shift allowances, looking across several months can give you a clearer picture of your usual income and spending.
The MoneyHelper budget planner is a free tool that can help you get started.
2. Find a budgeting approach that works for you
There isn’t one way to budget that works for everyone. One popular starting point is the 50/30/20 approach.
It divides your take-home pay, the money that reaches your account after deductions, into three areas:
- 50% for needs, such as housing, food, essential bills and minimum debt repayments
- 30% for wants, such as hobbies, eating out and treats
- 20% for savings and additional debt repayments
For example, with £2,000 take-home pay a month, that would mean £1,000 for needs, £600 for wants and £400 for savings and additional debt repayments.
These percentages are only a guide. What works for you will depend on your income, commitments and circumstances.
3. Get your budget ready for winter
Winter can bring extra costs, from heating and energy use to festive spending, food and travel.
Looking back at what you spent last winter can help you get a better idea of what might be coming this year. Your bank statements could be a useful starting point.
If you can, think about these costs before they arrive and include them in your budget. Even putting aside a small amount towards seasonal spending can make it easier to plan.
4. If your budget has gone off track
Things change. A different shift pattern, a change in overtime, an unexpected bill or an increase in everyday costs can all affect a budget that previously worked for you.
If things aren’t adding up, reviewing your budget can help you understand what’s changed and what options are available.
Some bills can have more serious consequences if they’re not paid. MoneyHelper’s bill prioritiser can help you understand which payments to deal with first.
If you’re worried about keeping up with payments, you don’t have to tackle it alone. Speaking to your providers early can help you understand what support might be available.
If you are in arrears or struggling to make payments, seek free debt advice as early as possible.
Free, independent support is also available from organisations including MoneyHelper and StepChange.
You can find more information on our managing debt webpage too.
Police officers, staff and their families can also find wider wellbeing support through Oscar Kilo, the National Police Wellbeing Service.
5. Give your savings a purpose
Having something to work towards can make saving feel more manageable.
Your goals might include annual bills, a holiday, home improvements or your longer-term plans for retirement.
It can also be useful to keep some savings separate for things you weren’t expecting, such as an urgent home repair or a sudden change in circumstances.
Whatever your starting point, try not to be discouraged if you can’t put away as much as you’d like. Building a regular savings habit, even with a small amount, can help you work towards greater financial resilience over time.
6. Think about life after work
Whether retirement feels a long way off or is getting closer, understanding what you may have to live on can help you plan ahead.
Depending on your circumstances, your retirement income could include a police or workplace pension, the State Pension, personal pensions and your own savings.
If you’ve worked for different employers, forces or in different careers, you may also have more than one pension.
A useful starting point is to make a list of the pensions you have and who manages them. You can then check the forecasts available from each provider.
You can also use the State Pension forecast on GOV.UK to find out how much State Pension you could receive and when you may be able to claim it.
Remember, pension forecasts are estimates rather than guarantees. Checking them from time to time, and when your circumstances change, can help you keep track of your plans.
If you’re unsure about decisions involving your pension or retirement, consider seeking appropriate regulated financial advice.
7. Check what support could be available
Your circumstances can change, and so can the support you may be entitled to.
It can be worth checking again following a change in your income, family or personal circumstances, even if you haven’t been eligible for support before.
The GOV.UK benefits and financial support checker can help you find out what support may be available.
There may also be help available with heating and energy costs during winter. Schemes and eligibility can change, so check the latest information on GOV.UK to understand what is currently available and whether you could qualify.
8. Plan for the unexpected
Thinking ahead isn’t just about saving. It can also mean making sure the right information and arrangements are in place if you couldn’t manage your finances yourself.
Things you may want to think about include:
- keeping important financial information somewhere safe and making sure someone you trust knows where to find it
- making or reviewing your will
- checking any beneficiary or nomination arrangements connected with your pensions
- finding out whether a Power of Attorney could be appropriate for you.
The rules and terminology around wills, inheritance and Powers of Attorney aren’t the same across all parts of the UK. Check the official guidance for where you live and consider taking legal advice if you’re unsure about your situation.
9. Make a regular financial check-in
Your finances are unlikely to stay the same forever, so your budget doesn’t have to either.
A pay rise, moving home, changes to your family, retirement or simply higher everyday costs can all be good reasons to take another look.
Checking in every few months, and whenever something changes, can help you understand where you stand and whether your plans are still working for you.
A few simple questions can get you started:
- Has my income changed?
- Have any of my regular bills gone up or down?
- Am I still comfortable with what I’m saving?
- When did I last check my pension information?
- Is there anything coming up that I need to budget for?
A little time spent checking in now can help you feel more prepared for what’s ahead.
Important information
This article provides general information only and does not constitute financial, pensions, tax or legal advice. Your circumstances are individual to you. If you’re unsure about a financial decision, consider seeking appropriate professional advice.
Slater House, Oakfield Road,
Cheadle Royal Business Park,
Cheshire, SK8 3GX
Cheadle Royal Business Park,
Cheshire, SK8 3GX

Stay in touch
Copyright © 2026 No1 CopperPot Credit Union
Number One Police Credit Union Limited trading as No1 CopperPot Credit Union is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority. Firm Reference Number (FRN) 213301. For details visit http://www.fca.org.uk